Before opening a business bank account in the U.S., gather your tax ID, identification for the people applying, and records showing your business’s legal name, ownership, and who can sign for it.
Then confirm two details with the bank you plan to use: who must attend and which documents the bank will accept. A two-owner LLC can have every document ready and still need another appointment because only one owner came to the branch.
What to gather before opening a business bank account
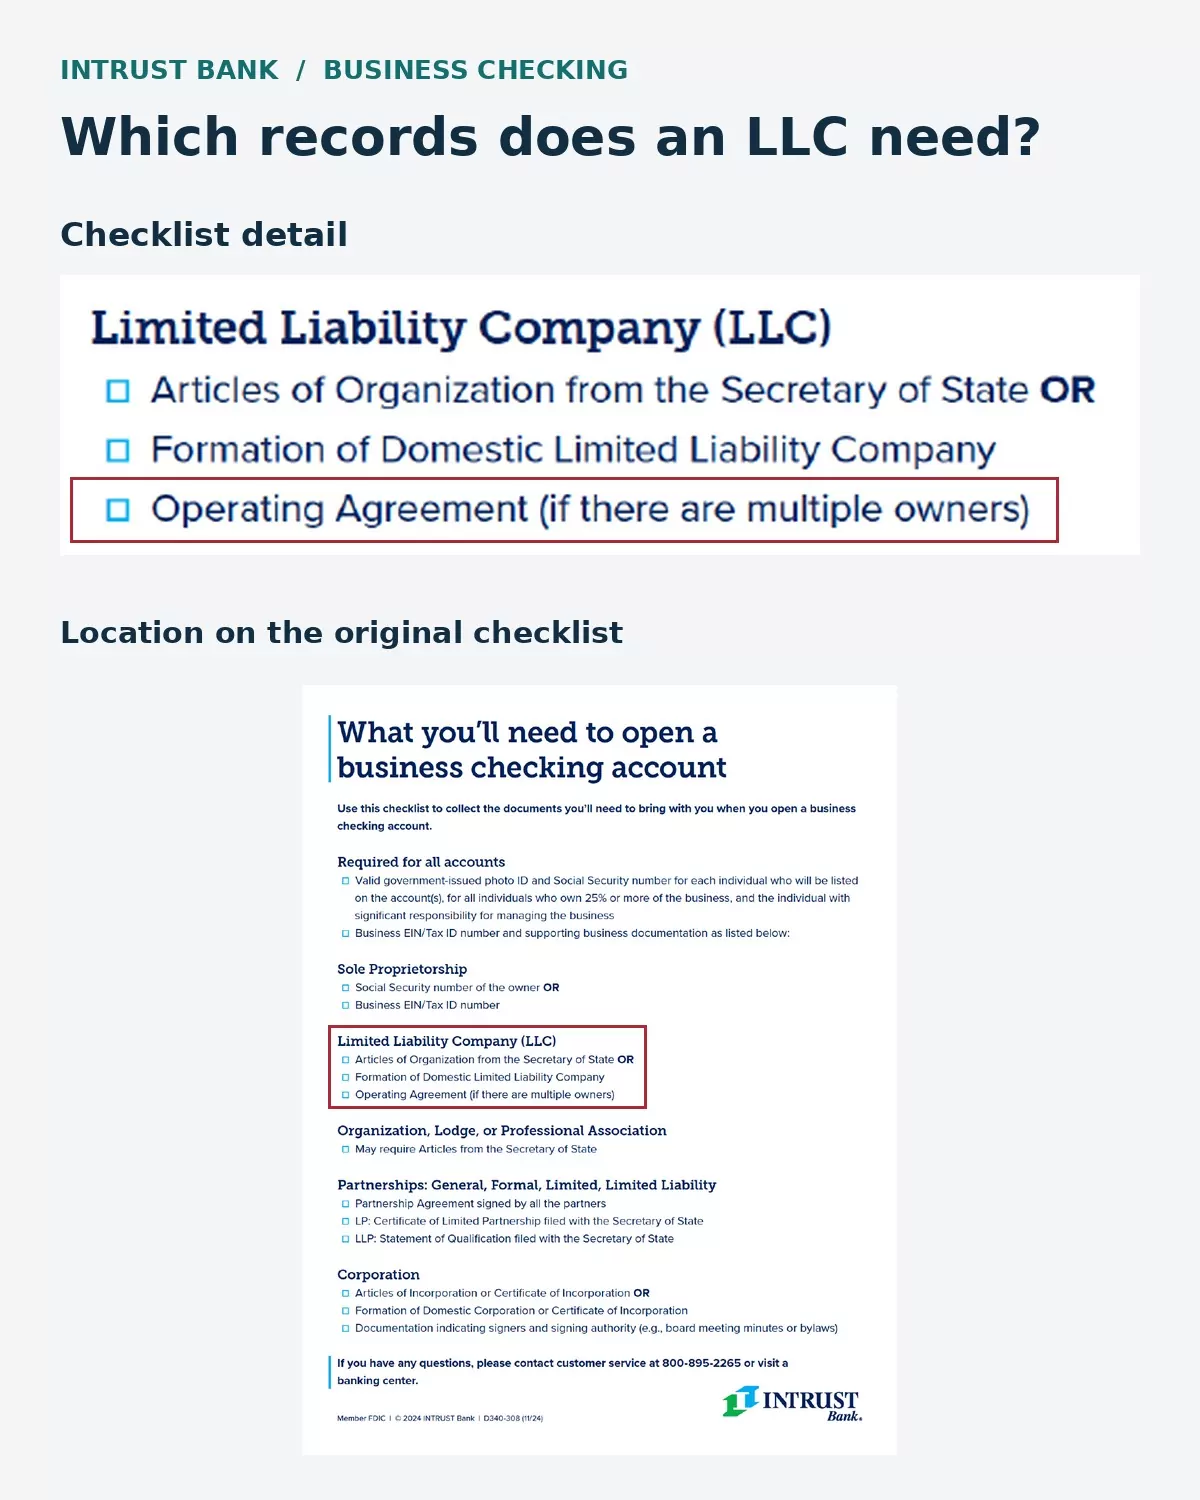
Start with the checklist for your legal structure. The U.S. Small Business Administration lists formation documents, ownership agreements, a tax ID, and a business license among the records banks commonly request. Your bank’s instructions will tell you which of those apply to you.
| If your business is a… | Have these records available | Confirm with the bank |
| Sole proprietorship | Your photo ID, Social Security number or employer identification number (EIN), and applicable trade-name registration | Which tax ID it accepts and what it needs if customers pay you under a business name |
| Partnership | EIN, partnership agreement, and applicable registration records | Which partners must attend and who can sign for the partnership |
| Limited liability company (LLC) | Formation record, operating agreement if available, ownership details, and the tax ID the bank requests | Whether the LLC is member-managed or manager-managed and whether you can apply online |
| Corporation | EIN, articles of incorporation, and records identifying the authorized officer | Which officer can open the account and whether the bank requires a banking resolution |
Treat these as starting points when you request the bank’s checklist. For example, Chase lists different attendance requirements for partnerships, LLCs, and corporations, and its online application supports only certain LLC ownership and management arrangements.
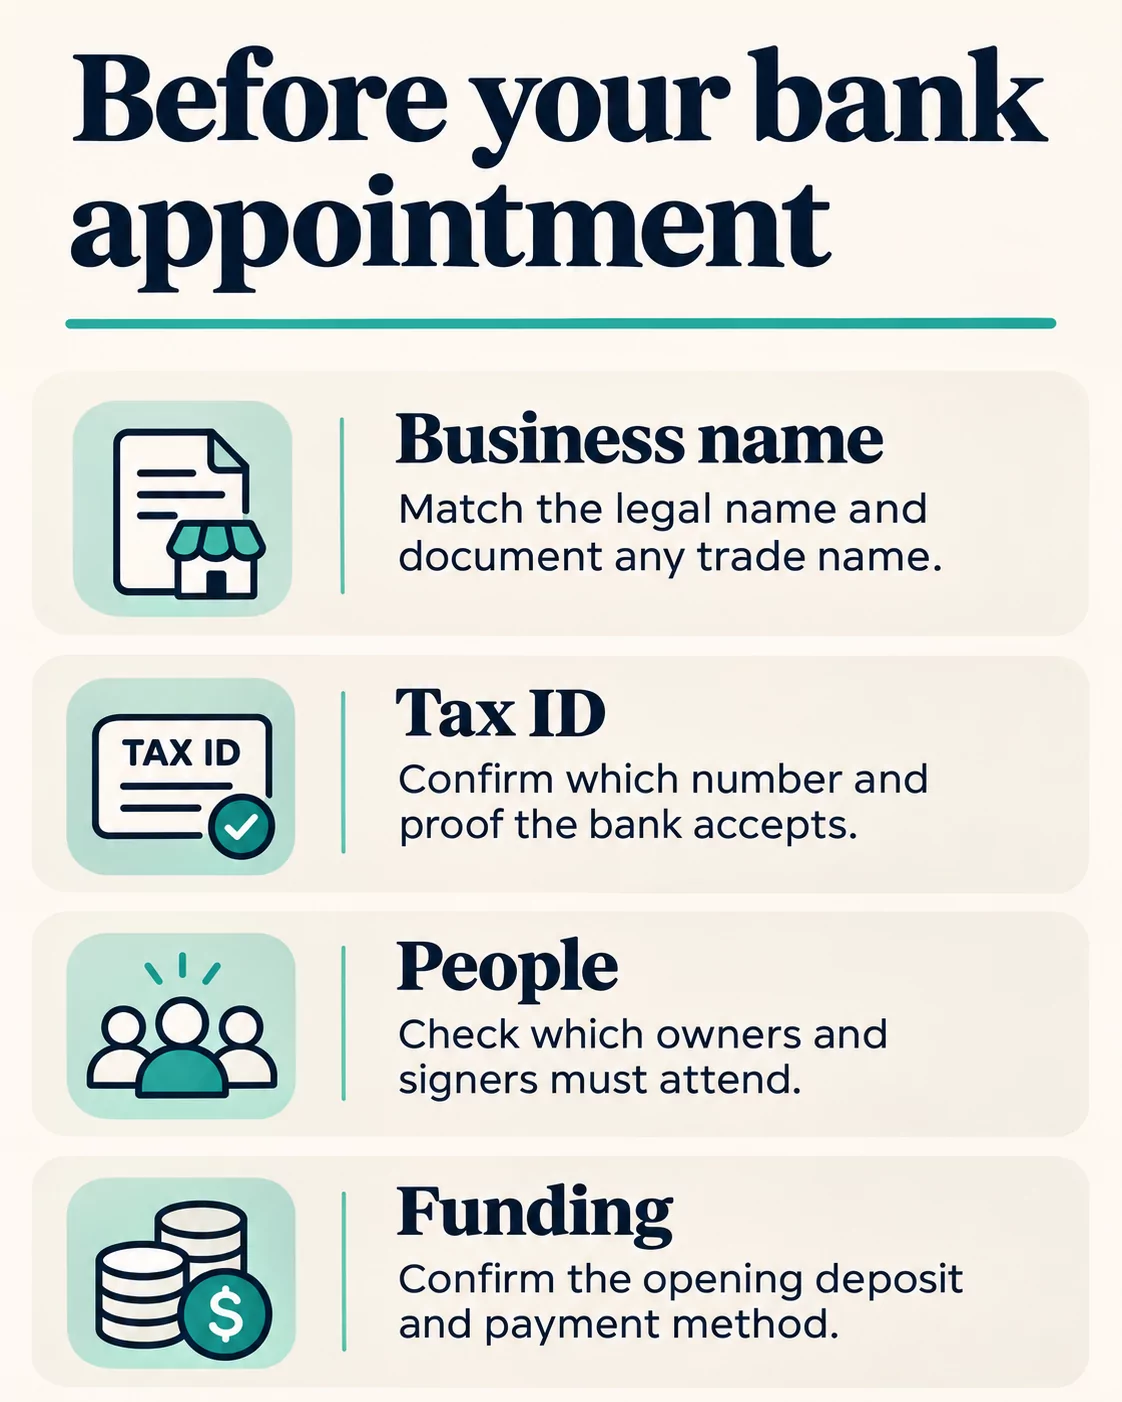
Match the business name to the name customers will pay
Put your formation or registration record beside a customer invoice. Check the full legal name, including “LLC” or “Inc.,” and identify any different name customers see. If you use a trade name, sometimes called a doing business as or DBA name, ask which document the bank accepts to connect it to the legal owner.
Suppose your company is North Street Design LLC, but your invoices say Studio North. Before sending the first invoice, ask the bank, “What do you need on file for us to deposit a check payable to Studio North?” That question gives the banker both names and the transaction you need the account to handle.
Set aside the tax ID and acceptable identification
An EIN is the federal tax identification number for a business. The SBA also lists a Social Security number as an option for a sole proprietorship. Check which identifier your bank accepts for your circumstances and whether it needs a document showing that number. If it asks for proof, find out which record and file format it accepts before you start the application.
Check personal identification separately. At Chase, for example, the LLC checklist calls for two forms of identification, including a primary or government-issued ID. Look up the accepted combination for each person attending. Someone who brings only a driver’s license could have the right primary ID and still be missing the second document.
Identify the owners, managers, and signers
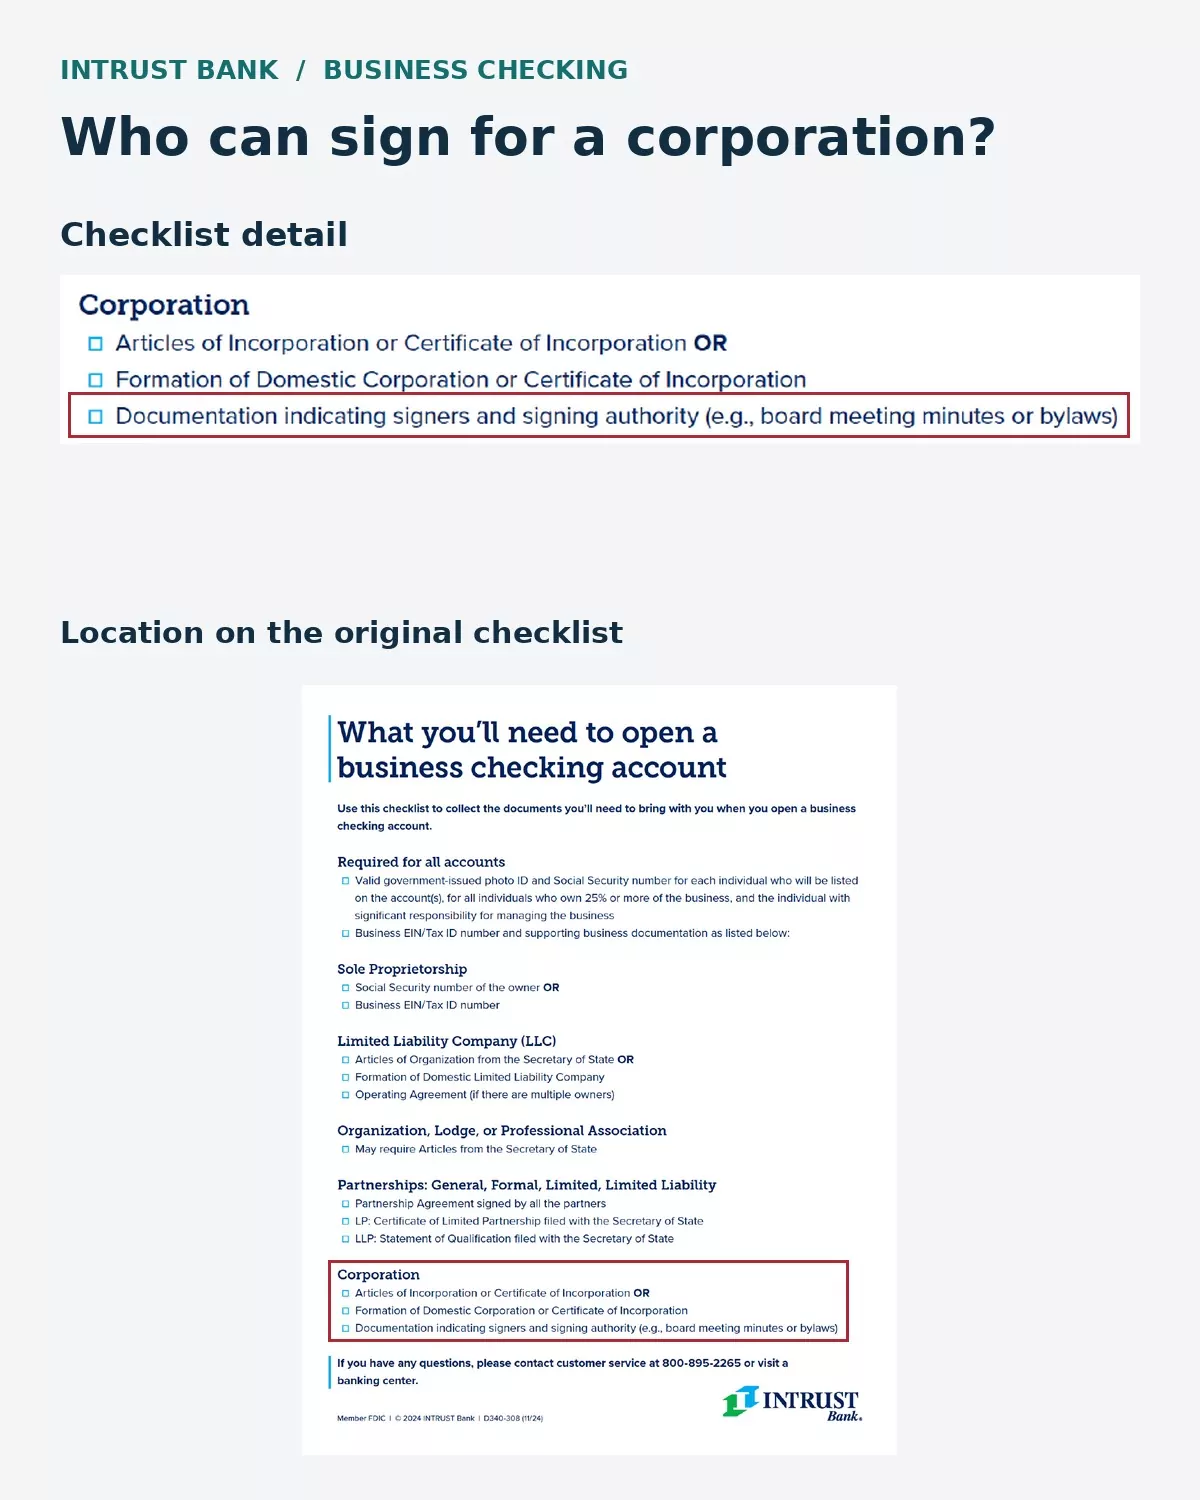
Make a short list with three columns: person, role, and authority. Record who owns the company, who manages it, and who should be able to sign on the account. Have current ownership percentages available if the application asks for them. A bookkeeper who needs to download statements may need different access from a partner who approves payments. Decide what each person needs before requesting access.
For an LLC, check the management arrangement in the company records before booking. Chase’s branch instructions call for all members of a member-managed LLC or all managers of a manager-managed LLC. If another business is itself a member or manager, Chase also calls for an authorized representative of that business. Ask your own bank what to do if a required participant is unavailable.
Price the account against an ordinary month
Pull together one month of expected activity before choosing the account. A café owner might count weekly cash deposits and change orders. A design consultant might count incoming client transfers, software payments, and an occasional international wire. If you are just starting, use estimates and label them as such.
Use those figures to ask specific questions about the bank’s fee schedule and services. The SBA recommends comparing fees, minimum balances, and transaction costs when choosing business banking services.
| Bring this estimate | Ask the bank |
| Lowest balance you expect before customers pay | How is the monthly fee waiver calculated, and would this balance qualify? |
| Cash deposited in a typical month | How much cash can I deposit before a fee applies, and where can I make deposits? |
| Number and types of payments you send | Which transactions count toward an allowance, and what does an additional transaction cost? |
| Amount available for the opening deposit | How much is due, when is it due, and how can I fund it? |
The opening deposit and the balance needed to waive a monthly fee answer different questions. Record both figures so you can judge whether the account will still suit the business after the first month.
Confirm the appointment against your actual paperwork
Give the bank enough detail to identify the right application route. “Can I open an account online?” is easy to answer in general. “Can two members of a member-managed LLC apply online if one lives out of state?” gets you an answer you can act on. Some banks distinguish between single-owner and multi-owner businesses when deciding who can apply online.
Use this short call script before booking:
“Our business is a [legal structure] registered in [state]. Our legal name is [name], and customers pay us as [trade name, if applicable]. We have [number] owners, and [role] will open the account. Who needs to attend? Which IDs and business records do you accept? Do you need originals or certified copies? How do we make the opening deposit?”
Before the first customer payment
The most useful final check before opening a business bank account is to trace one payment all the way through. What name will the customer put on the check? Who can deposit it? Who can see that it cleared? Take any unresolved answers to the bank alongside your paperwork. You’ll arrive ready to set up an account for the way your business actually gets paid.