Credit card processing fees are easier to compare when you start with what your business actually pays each month. A low advertised percentage can become expensive once transaction charges, recurring services and contract terms enter the calculation. The useful question is how much a provider would charge for your sales mix—and what you would receive for that cost.
This guide uses US payment terminology and documentation-based analysis. The worked examples are hypothetical calculations, not provider quotes or results from a live merchant account.
What credit card processing fees pay for
A card payment involves several parties. In a typical four-party arrangement, the issuing bank serves the cardholder, the acquiring side serves the merchant, and a card network connects them. The processor supplies transaction services. A business may buy several of these functions through one provider, even when other organizations perform parts of the work.
The Government Accountability Office’s explanation of card acceptance costs separates the merchant discount into interchange, network fees and acquiring or processing charges. Interchange generally flows from the acquiring bank to the issuing bank; networks establish interchange schedules. Network charges support the network’s services. The remaining processor or acquirer charge pays for its role. Arrangements vary, so this is a useful framework rather than a universal diagram for every network.
That distinction matters during negotiations. A provider’s markup is different from an underlying network or interchange charge. Ask which component a proposed discount changes and whether it also changes the total you pay.
A gateway is another part of the payment setup, particularly online. It is not simply another name for the processor. Our explanation of payment gateways versus payment processors helps identify which services are bundled and which may be billed separately.
Compare the pricing model before comparing the rate
Two quotes can display similar percentages while covering different costs. Establish what each percentage includes before placing the offers side by side.
| Model | How to read the offer | Decision to make |
|---|---|---|
| Flat-rate | A bundled transaction rate, often with a fixed amount per payment. Separate rates or extras may apply to different transaction types. | Does simpler forecasting justify the cost for your actual mix of sales? |
| Interchange-plus | Underlying interchange and relevant network charges plus a disclosed provider markup. | Can you understand the pass-through charges and reconcile the markup? |
| Subscription or membership | A recurring charge combined with transaction costs; the precise inclusions depend on the agreement. | Is your volume sufficient to justify the recurring commitment? |
| Tiered | Transactions fall into pricing buckets under the provider’s qualification rules. | Which transactions land in each tier, and can the provider demonstrate that using your own sales? |
No model is automatically cheapest. A seasonal retailer may prefer a manageable cost in quiet months. A business with steady volume may place more value on transparent markup and reporting. A provider that saves staff time on reconciliation can also be worth more than its transaction rate suggests—but that benefit should be demonstrated, not assumed.
Why average transaction size changes the result
A fixed charge per payment has a larger effect on a small purchase. Consider an illustrative bundled rate of 2.6% plus $0.10 per successful transaction. These numbers are chosen only to show the arithmetic.
| Sale | Percentage charge | Fixed charge | Total fee | Share of sale |
|---|---|---|---|---|
| $10 | $0.26 | $0.10 | $0.36 | 3.60% |
| $100 | $2.60 | $0.10 | $2.70 | 2.70% |
The advertised percentage is identical, but the effective cost differs. For a coffee shop, the fixed component deserves close attention. For a business taking larger invoices, the percentage component may have more influence. Calculate both using your transaction count and volume rather than relying on an industry average.
Calculate your monthly effective cost
For an initial comparison, divide the card acceptance fees included in your analysis by gross card sales for the same period, then multiply by 100. Define the scope consistently. If one quote includes a required gateway subscription and another lists it separately, include that subscription in both totals.
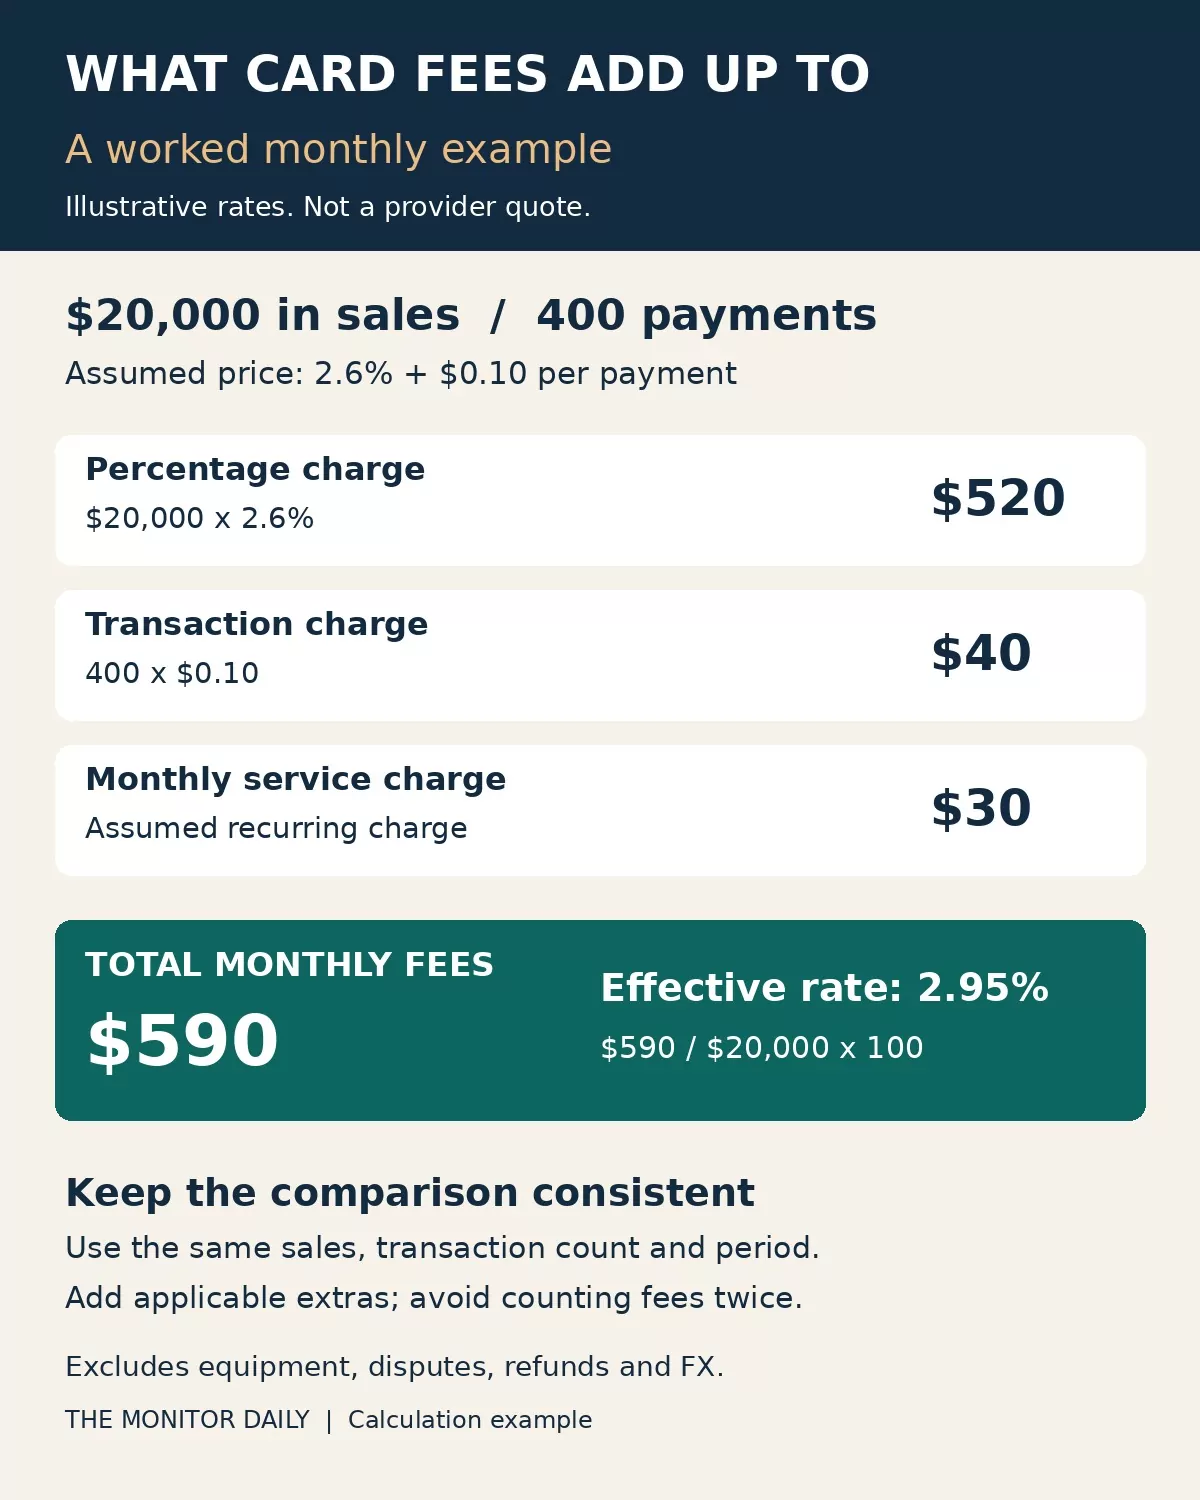
Suppose a hypothetical business processes $20,000 across 400 successful card transactions in one month. At the illustrative rate above, its percentage fees would be $520 and its fixed transaction fees $40. Add an assumed $30 recurring service charge and the total becomes $590.
$590 ÷ $20,000 × 100 = 2.95%.
This is an all-in effective rate for the stated example, not a market benchmark. It excludes equipment, disputes, refunds, currency conversion, and other events. If those costs apply to your business, model them separately and then build an appropriately scoped total.
To compare a second offer, give it the same volume, transaction count, payment channels and card mix. An interchange-plus estimate also needs an explicit assumption for underlying costs. Comparing its markup alone with a bundled rate is not a like-for-like comparison.
Find charges that the headline rate leaves out
“Hidden” often means missing from the sales summary rather than absent from the contract. Request the complete fee schedule and applicable agreements before signing. The following questions turn a vague quote into something you can evaluate.
- Is there a monthly account, gateway, software, or minimum-billing charge?
- Are authorization attempts, completed payments, and batch submissions billed differently?
- What happens to the original processing fee when a customer receives a refund?
- What dispute fees apply, and are any returned after a successful challenge?
- Do cross-border cards, currency conversion, or manually entered transactions change pricing?
- Is hardware purchased, rented, or leased under a separate agreement?
- What notice, renewal, and early-exit terms apply?
These are contract questions, not claims that every provider imposes every charge. Ask for a written answer tied to the specific plan being offered. A sales conversation about “no monthly fees” does not resolve a separate equipment lease or paid software subscription.
Security-related billing also needs interpretation. A fee bearing a compliance label is not, by itself, proof that your business has satisfied its obligations. Ask what service the fee purchases and which tasks remain your responsibility.
Reconcile fees without mistaking every deduction for a cost
The gap between gross sales and a bank deposit is not automatically your processing fee. A refund principal returns money to a customer. A disputed payment may remove the original sale amount as well as trigger a separate fee. A reserve can withhold funds without making the withheld amount a fee. Settlement timing can move transactions between reporting periods.
Build a bridge from the processor’s activity report to the payout report and then to the bank statement. Identify sales, refunds, adjustments, withheld or released reserves, and actual fees separately. Check whether processing charges were netted from payouts or debited later. Otherwise, you could count the same expense twice or miss it entirely.
Use a full billing period for the fee comparison and keep the supporting reports. If payouts cross month-end, reconcile the timing difference instead of forcing the numbers to match. An unexplained difference is a reason to investigate the transaction detail, not a reason to label the whole amount “bank charges.”
Build a quote comparison your team can reproduce
Choose a representative month and, if your business is seasonal, a second month with materially different activity. Remove customer and card details before sharing information for a quote. A provider generally needs the commercial pattern, not unrestricted access to sensitive customer records.
| Input or question | What to record |
|---|---|
| Sales pattern | Gross card volume, successful transaction count and average ticket |
| Acceptance channels | In-person, online, recurring and manually entered activity |
| Card and geographic mix | Relevant breakdown available in your existing reports |
| Recurring requirements | Gateway, software, account and equipment commitments |
| Event costs | Refund and dispute assumptions, with principal separated from fees |
| Exit and change terms | Notice periods, renewal, price changes and equipment obligations |
| Evidence | Dated written quote, assumptions and the agreement that governs it |
Ask each provider to calculate a total for that identical scenario and explain every exclusion. Then test a quieter month or a lower average ticket. This exposes an offer that looks attractive only under one optimistic assumption.
Keep operational requirements beside the cost calculation: reconciliation exports, integration with your accounting system, settlement arrangements and access controls. A lower fee is less useful if the resulting workflow creates avoidable manual work or prevents your team from explaining the books.
Keep credit, debit and customer surcharges separate
Do not assume a debit interchange rule caps credit card processing fees. The Federal Reserve’s Regulation II guide concerns debit-card interchange and routing, with exemptions and specific coverage conditions. It is not a general ceiling on the total price a merchant pays to accept credit cards.
Likewise, passing costs to customers is a separate decision from negotiating a processing agreement. Before introducing a surcharge or discount program, verify the rules applicable to your location, card types, network and acquiring agreement. A provider’s advertised feature does not settle every legal or contractual requirement.
Make credit card processing fees a monthly management check
The most useful measure of credit card processing fees is a documented total that your team can explain. Keep the sales denominator consistent, separate genuine fees from other deductions and compare offers using your own transaction pattern. Start with one representative statement, obtain a complete written quote and resolve any unexplained line before committing. That process gives you a stronger purchasing decision than choosing the smallest percentage on a pricing page.