A business banking meeting is more useful when you arrive with a clear request, reliable numbers and a short list of decisions to make. Whether you are opening an account, discussing finance or reviewing payment services, prepare enough information for the banker to understand how your business operates—and enough questions to judge whether the proposed service fits.
For US small-business owners, the preparation has three parts: confirm the purpose of the appointment, assemble the relevant evidence and decide what you need in writing afterward. A complete folder helps, but a productive conversation also explains what the documents mean.
This guide combines current public agency guidance with a practical preparation framework. It is research-based, not an account of an actual banking appointment. Requirements vary by institution, entity, product and applicant; the bank’s current checklist should govern what you submit.
Define the outcome of your business banking meeting
Start with one sentence: “By the end of this appointment, I want to understand whether this bank can provide…” Finish it with a specific need. It might be an operating account with suitable payment controls, a way to handle more cash deposits or an initial assessment of a financing request.
Tell the bank that purpose when booking. A general account-opening appointment may not include a commercial lender or someone who can explain treasury services. Ask who will attend, what they can decide and which questions require another specialist.
| Meeting purpose | Prepare first | Useful outcome |
|---|---|---|
| Open or change an operating account | Entity details, ownership and authority information, expected account activity | Eligibility, required documents, fees and onboarding steps |
| Discuss borrowing | Amount, use of funds, financial position and repayment assumptions | Suitable application route, evidence required and next review |
| Review payments and access | Current workflow, users, transaction volumes and control problems | A proposed configuration, pricing and implementation responsibilities |
| Resolve an existing service problem | A dated incident summary and relevant transaction references | Named case owner, next action and escalation route |
Keep unrelated problems in a separate list. If you have only a short appointment, a discussion about payment permissions should not disappear into an unplanned conversation about every product the bank offers.
Ask for the document checklist before collecting everything
Request the checklist for your actual legal structure and product. Ask whether the bank requires originals, certified copies or electronic uploads, who must attend and whether all owners or signers must complete separate steps. Confirm the appointment format and the secure method for sending sensitive information.
The SBA’s business-account guidance identifies tax identification, formation documents, ownership agreements and business licenses among common account-opening documents, while noting that banks may request more. Treat that as a starting point rather than a universal acceptance list.
Create a simple index of what you have, what the bank requested and what remains missing. Check that names and addresses agree across the relevant records. If an address or ownership detail has changed, flag the discrepancy and ask what evidence is needed to update it. Do not alter a document to make it appear consistent.
Use the bank’s verified upload process. Confirm unexpected requests through a contact channel you already trust. Passwords and one-time authentication codes do not belong in a preparation packet, and unnecessary copies of sensitive documents should not circulate around your team.
Build a one-page business brief
The brief helps the banker connect your records to the service you want. Use plain language to explain what you sell, who pays you and how money moves through the business. Keep estimates separate from actual results and date the information.
| Field | What to write |
|---|---|
| Business and request | Legal name, trading name if applicable, entity type and the decision you want |
| Activity | Products or services, principal customer types and how orders are fulfilled |
| Money movement | Usual incoming and outgoing payment methods, approximate volumes and relevant currencies |
| Seasonality | When collections and spending rise or fall, with the reason |
| People and access | Who owns the business, who is authorized to act and which users need which functions |
| Evidence and gaps | Documents supporting the request and any material information still outstanding |
Do not inflate turnover or describe an unsigned prospect as a committed customer. A useful explanation can be short: “Most invoices are collected after delivery, while supplier costs arrive earlier.” Follow it with the records that show the timing and the service you want to discuss.
Make the financial figures tell one consistent story
For a financing discussion, ask which financial statements, tax records and forecasts the lender needs and for what periods. One lender’s published checklist is not a rule for every loan. A startup, an established company and a property purchase can require different supporting material.
Reconcile the documents you do provide. The bank balance, cash in your books, revenue and profit are different measures. If two figures differ, prepare the explanation rather than hoping the banker will overlook it. Our guide to bank statements versus accounting ledgers explains common timing and recording differences.
The Office of the Comptroller of the Currency’s small-business lending guidance emphasizes business cash flow as the primary repayment source for most small-business loans. That is a reason to explain the timing and reliability of cash coming in, alongside the amount you want to borrow.
Prepare a forecast with visible assumptions: collection dates, expected sales, supplier payments, operating expenses and existing debt obligations. Show what happens if an important receipt arrives later than planned. This is an exercise in identifying exposure, not a promise that the forecast will come true.
For example, a hypothetical contractor expecting a customer payment after buying materials should show the purchase date, payment due date and remaining cash during the gap. The conversation can then address the timing mismatch. A round loan request without that explanation gives the banker less to evaluate.
Turn the bank’s proposal into questions you can compare
Bring your own activity assumptions to a fee discussion. Ask the banker to explain the proposed account or service using a representative month of your transactions. Record what the estimate includes and what it leaves out.
- Which recurring, transaction and exceptional charges could apply to this pattern of activity?
- How is any minimum-balance condition measured, and when is a charge assessed?
- Which payment limits, processing cutoffs and availability conditions apply?
- Which users can prepare, approve and release payments, and can those permissions be separated?
- What support route applies to an urgent payment problem?
- Which integrations, exports or implementation services are included?
- What would changing or closing the arrangement require?
For borrowing, add questions about the rate structure, fees, repayment schedule, security, any personal guarantee and reporting obligations. Ask for explanations of terms you do not understand and seek appropriate professional advice before making consequential commitments. An initial conversation is not a substitute for reading the actual documents.
If the meeting involves access changes, distinguish legal authority from an online permission setting. Our explanation of business bank account roles and signatories can help you prepare the questions. Do not assume a job title automatically grants either type of access.
Use an agenda that leaves time for decisions
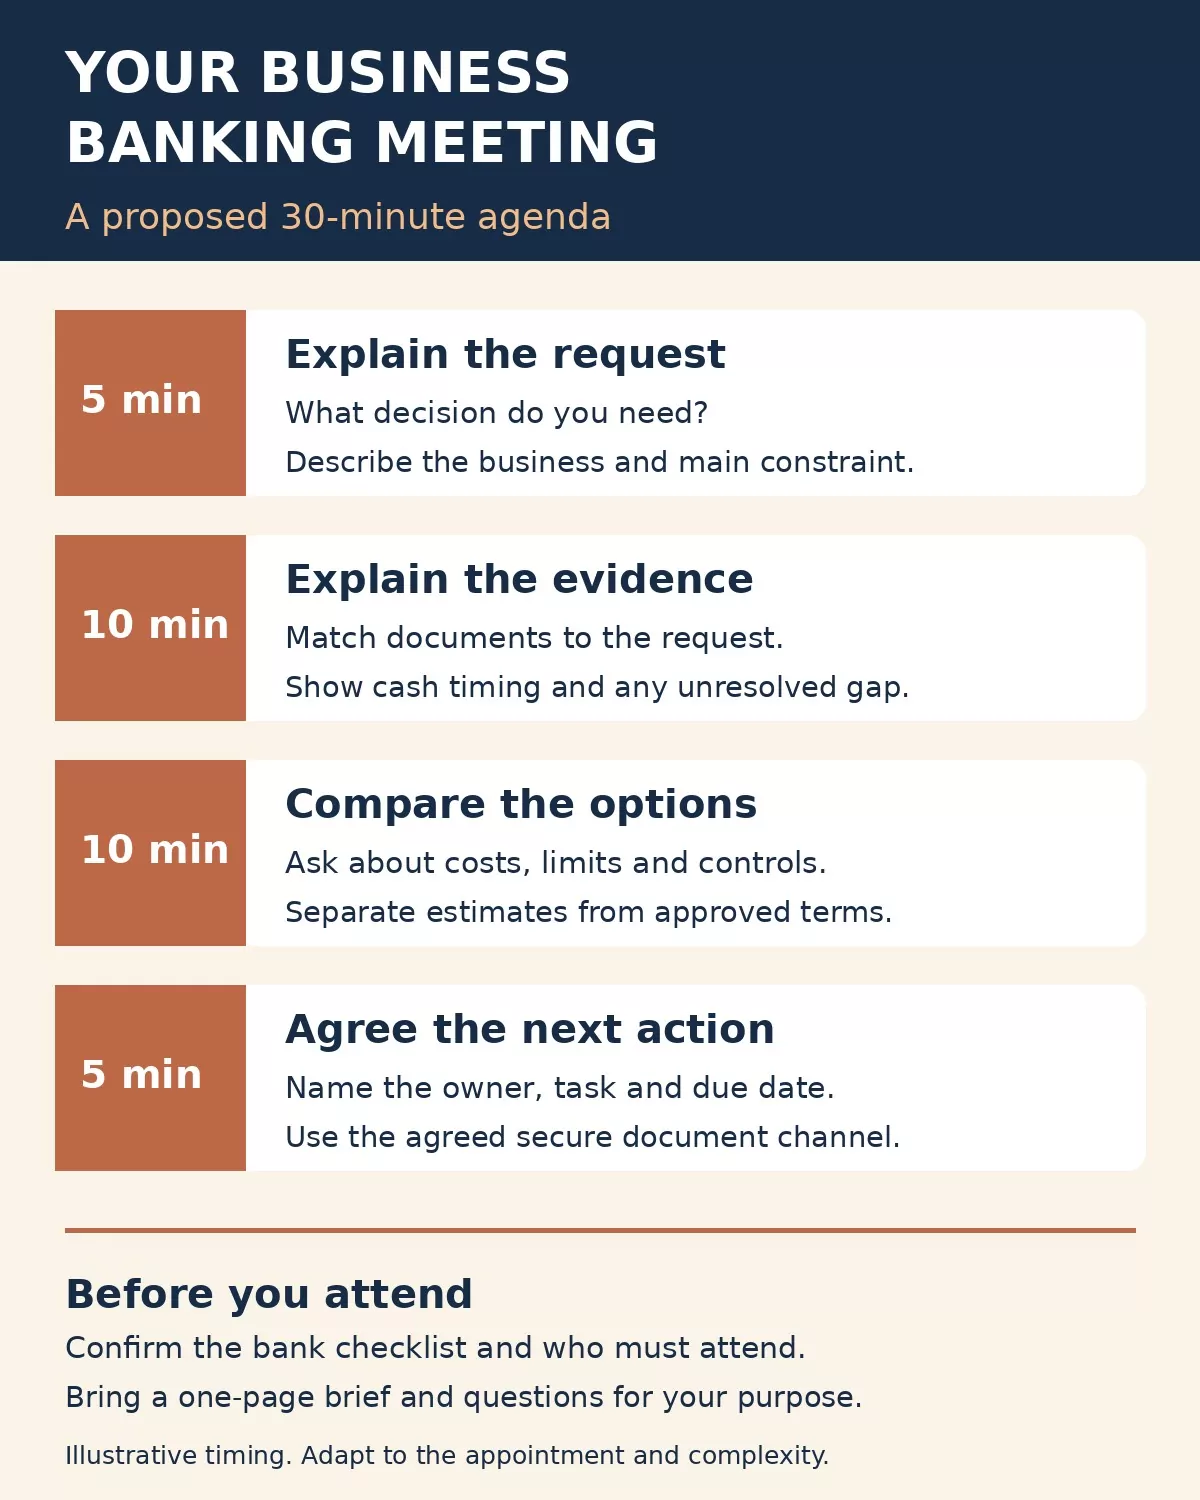
A proposed 30-minute agenda could reserve five minutes for the business and request, ten for documents or the financial position, ten for options and questions, and five for next actions. This is an illustrative allocation; adjust it to the appointment and complexity.
Open with the decision you need. Then explain the main constraint: cost, cash timing, access control or a service limitation. Let the banker identify missing information before spending the whole appointment on a detailed presentation.
Ask whether a statement is an estimate, a policy explanation, an application requirement or an approved offer. Those are different stages. A positive conversation does not guarantee an account, credit approval or a particular price.
Leave with a short action record
Before finishing, repeat what each side will do next. Record the responsible person, document or decision, delivery channel and agreed timing. If the bank has not given a date, mark it as unconfirmed rather than inventing one.
| Action | Owner | Evidence of completion |
|---|---|---|
| Provide a requested document | Named person in your business | Submission through the agreed secure channel |
| Clarify pricing or eligibility | Named bank contact | Written answer or applicable product terms |
| Arrange specialist review | Person who agreed to coordinate it | Confirmed next appointment or referral |
Send a concise recap through the agreed channel. Correct misunderstandings promptly and keep the relevant version of every document. If an important question remains unanswered, preserve it as an open item instead of treating the meeting as a completed application.
Prepare for the next business banking meeting with a clearer decision
The best preparation for a business banking meeting is a clear request supported by records you can explain. Confirm the bank’s checklist, bring a concise business brief, connect the financial figures to your actual cash needs and ask for written next steps. You should leave knowing what is available, what is still uncertain and what must happen before you can make a sound decision.